Home/Insurance solutions/Industrial All Risk Policy (IAR)
INSURANCE · RISK · ADVISORY

Industrial All Risk Policy (IAR).

Protection structured around real-world risk.

Comprehensive all-risk industrial insurance designed for large-scale manufacturing facilities and industrial estates with sum insured of ₹100 Crore and above, integrating Material Damage and Business Interruption under one unified policy.

Thoughtful advice. Clear options. Support through the policy journey.
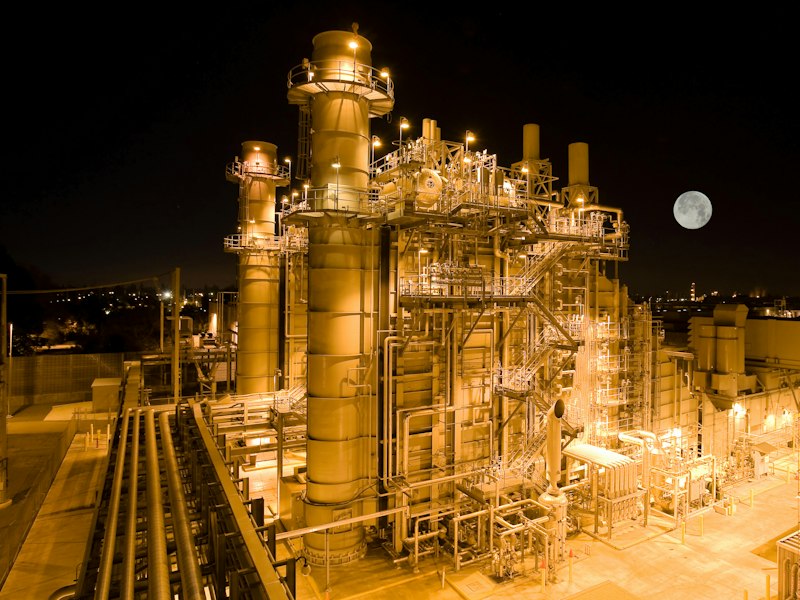
Large-scale industrial manufacturing plant, refinery and complex facilityGITVISHA · RISK ADVISORY
Risk, understood.Start with what matters
Cover that fitsSubject to policy terms
CRITICAL VULNERABILITIES & EXPOSURES

Real-world risks this policy is engineered to solve.

Commercial and personal risks rarely follow idealized assumptions. These are the critical financial pitfalls, claim traps, and operational vulnerabilities that proper policy structuring actively mitigates.

High-Impact Vulnerability01

Electrical Short-Circuit & Rapid Flame Spread

High electrical loads, aging transformer panels, or overheated machine bearings igniting nearby packaging or combustible stock.

Impact: Total plant destruction, structural buckling, and immediate halt of all ongoing operations.
Policy Solution: Standard Fire & Special Perils (SFSP) with Reinstatement Value and Debris Removal endorsements.
High-Impact Vulnerability02

The Underinsurance & Average Clause Trap

Insuring factory buildings or machinery at historic balance-sheet book value instead of true current replacement cost.

Impact: In a ₹10 Cr loss with 40% underinsurance, the insurer legally pays only ₹6 Cr, leaving ₹4 Cr uncovered.
Policy Solution: Pre-quote valuation benchmarking and Agreed Value / Reinstatement Value clauses with escalation extensions.
High-Impact Vulnerability03

Monsoon Inundation & Flash Flooding (STFI)

Severe cloudbursts, blocked municipal drains, or river overflows inundating ground-level factory floors and basements.

Impact: Submerged electrical motors, rusted CNC spindles, and completely ruined raw materials.
Policy Solution: Storm, Tempest, Flood & Inundation (STFI) cover with low deductible thresholds and rapid survey advocacy.
UNDERSTAND YOUR OPTIONS

Protection begins with the right questions.

These are discussion points, not a promise that every risk is covered. Final cover depends on policy wording and insurer acceptance.

01

Section I – Material Damage (All Risk)

Accidental physical loss or damage to buildings, plant, machinery, electrical networks, and inventory from all causes not specifically excluded

02

Comprehensive Perils Integration

Unifies Fire & Special Perils (SFSP), Burglary, Accidental Damage, and Machinery Breakdown (MBD) under single-point coverage

03

Section II – Business Interruption (FLOP)

Loss of Gross Profit resulting from turnover reduction following an insured Section I physical loss, including standing charges

04

Increased Cost of Working (ICOW)

Additional operational expenditure incurred to maintain production schedules or secure alternate manufacturing facilities

05

Reinstatement Value & Capital Additions

New replacement cost settlement basis plus automatic 5% to 10% cover for in-year plant expansions

06

Specialized Industrial Endorsements

Professional architects/engineers fees, debris removal expenses, and decontamination/cleanup extensions

WHO IT MAY SUIT

Built around your real-world exposure.

The right structure starts with understanding your assets, operations, people and contractual responsibilities.

Large manufacturing plants, chemical processing units, and pharmaceutical complexes
Automotive, steel, engineering, and heavy fabrication industrial facilities
Power generation plants, petrochemical refineries, and textile mills
Multi-location industrial conglomerates with overall asset value exceeding ₹100 Crore
BEFORE YOU CHOOSE

Details that make a difference.

Compare more than price. Review limits, deductibles, exclusions and policy conditions.

01

Eligibility benchmark: Total Indian asset sum insured across all locations typically ₹100 Crore or above

02

Accurate computation of Gross Profit and definition of standing charges (indemnity period: 12, 18, or 24 months)

03

Underinsurance tolerance: Negotiating agreed margin clauses (typically 10% to 15%) to avoid average clause penalties

04

Compliance with Tariff Advisory Committee (TAC) fire protection norms (sprinklers, hydrants) to maximize tariff discount credits

GOOD TO KNOW

Questions, answered.

Need more clarity? Send us your requirement and our team can help explore the next step.

Ask our team
What is the key difference between Industrial All Risk (IAR) and Standard Fire (SFSP)?

SFSP is a 'named perils' policy that only covers specific listed causes of loss (fire, lightning, flood, storm). IAR is an 'All Risk' policy that covers every accidental physical damage or destruction unless specifically excluded, while automatically integrating Machinery Breakdown and Business Interruption (FLOP).

What is the eligibility threshold for an Industrial All Risk policy in India?

In the Indian insurance market, IAR policies are designed for industrial and manufacturing units with a total sum insured (Material Damage + Business Interruption) of ₹100 Crore or more across one or multiple locations in India.

Does IAR cover both mechanical breakdown and loss of profit from that breakdown?

Yes. Section I of an IAR policy incorporates Machinery Breakdown (MBD), and Section II (Business Interruption) can be structured to cover loss of profits resulting from machinery breakdown (MLOP) as well as fire (FLOP), ensuring seamless protection.

LET’S TALK ABOUT YOUR RISK

Make your next decision with more clarity.

Tell us about your requirement. Your email application will open with the enquiry ready to send.

A conversation focused on your needs
Options subject to underwriting
Clear next steps, without pressure

Request a consultation

Fields marked * are required.

Your details are transmitted securely to our risk advisory team. We maintain strict confidentiality.