Home/Insurance solutions/Business Interruption Insurance
INSURANCE · RISK · ADVISORY

Business Interruption Insurance.

Protection structured around real-world risk.

Consider cover for financial impacts when insured physical loss disrupts operations.

Thoughtful advice. Clear options. Support through the policy journey.
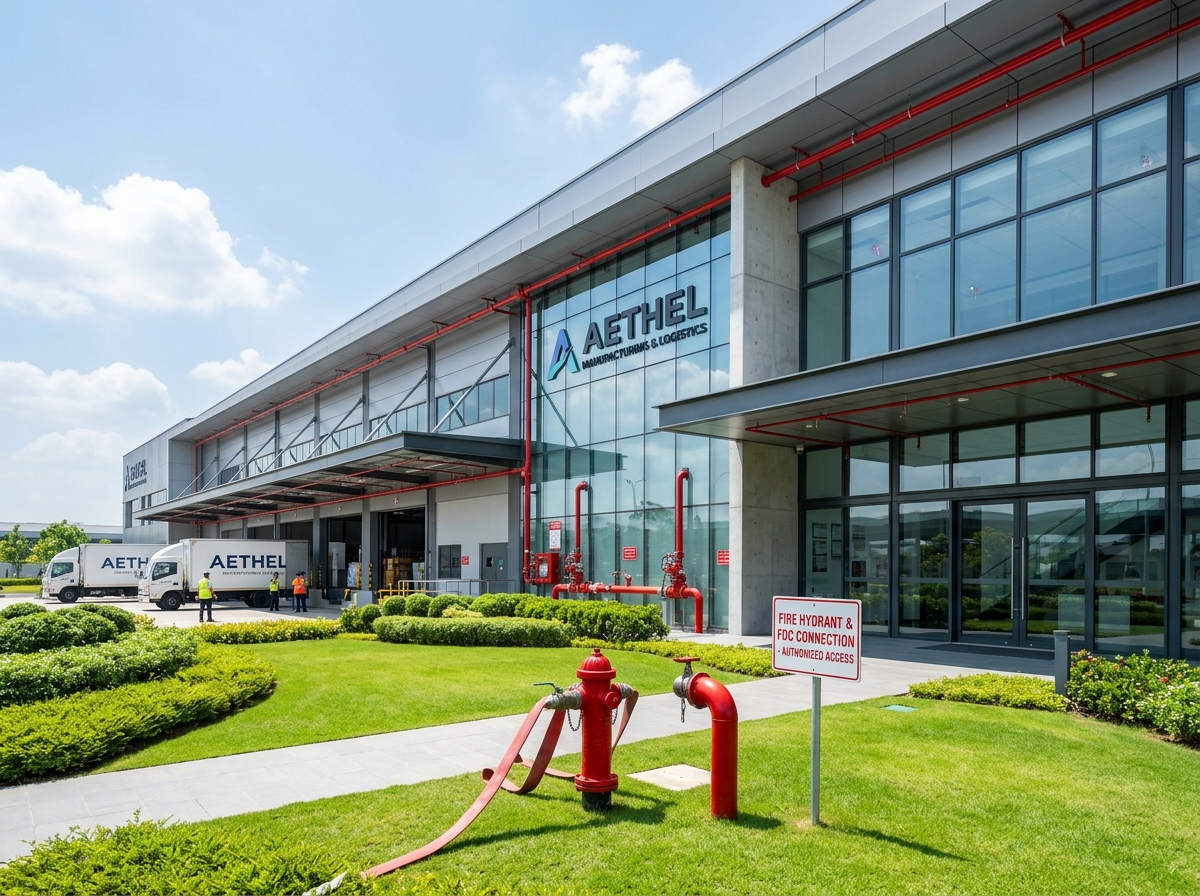
Commercial plant and business continuity operationsGITVISHA · RISK ADVISORY
Risk, understood.Start with what matters
Cover that fitsSubject to policy terms
CRITICAL VULNERABILITIES & EXPOSURES

Real-world risks this policy is engineered to solve.

Commercial and personal risks rarely follow idealized assumptions. These are the critical financial pitfalls, claim traps, and operational vulnerabilities that proper policy structuring actively mitigates.

High-Impact Vulnerability01

Ongoing Fixed Overhead Burn With Zero Factory Revenue

A major factory or warehouse fire shutting down operations for 6 to 18 months during structural rebuild.

Impact: While sales stop instantly, fixed bank EMIs, executive payroll, property leases, and taxes must still be paid.
Policy Solution: Loss of Profits insurance covering Gross Profit, Standing Charges, and debt servicing during restoration.
High-Impact Vulnerability02

Permanent Customer Attrition During Lengthy Downtime

Protracted production stoppage forcing long-term enterprise clients to migrate to competing manufacturers.

Impact: Permanent loss of market position even after the physical plant is completely rebuilt.
Policy Solution: Increased Cost of Working (ICOW) funds allowing you to outsource production to maintain client deliveries.
High-Impact Vulnerability03

Supply Chain & Customer Dependency Shocks

A catastrophic fire occurring at the premises of your sole raw material supplier or anchor buyer.

Impact: Complete operational paralysis for your business despite zero physical damage to your own property.
Policy Solution: Contingent Business Interruption (CBI) extension extending cover to critical supplier and customer premises.
UNDERSTAND YOUR OPTIONS

Protection begins with the right questions.

These are discussion points, not a promise that every risk is covered. Final cover depends on policy wording and insurer acceptance.

01

Insured loss of gross profit or

Insured loss of gross profit or revenue as defined

02

Increased cost of working where covered

Increased cost of working where covered

03

Indemnity period and triggers according to

Indemnity period and triggers according to wording

WHO IT MAY SUIT

Built around your real-world exposure.

The right structure starts with understanding your assets, operations, people and contractual responsibilities.

Manufacturing and processing units
Businesses dependent on key premises or equipment
Operations with supply dependencies
BEFORE YOU CHOOSE

Details that make a difference.

Compare more than price. Review limits, deductibles, exclusions and policy conditions.

01

Underlying property damage cover

02

Financial records and gross profit calculation

03

Indemnity period and exclusions

GOOD TO KNOW

Questions, answered.

Need more clarity? Send us your requirement and our team can help explore the next step.

Ask our team
Does it cover every shutdown?

No. The interruption must meet policy triggers and conditions.

Can supplier disruption be covered?

Some policies may offer specified extensions, subject to wording and limits.

LET’S TALK ABOUT YOUR RISK

Make your next decision with more clarity.

Tell us about your requirement. Your email application will open with the enquiry ready to send.

A conversation focused on your needs
Options subject to underwriting
Clear next steps, without pressure

Request a consultation

Fields marked * are required.

Your details are transmitted securely to our risk advisory team. We maintain strict confidentiality.